Fund managers like Clicks, because Clicks is a very steady business. It grows its earnings and its dividends steadily, year after year. But something bothers them, and that is why the price is a bargain. These are my own views and what I am watching, not instructions to anyone.
The price has halved, so why?
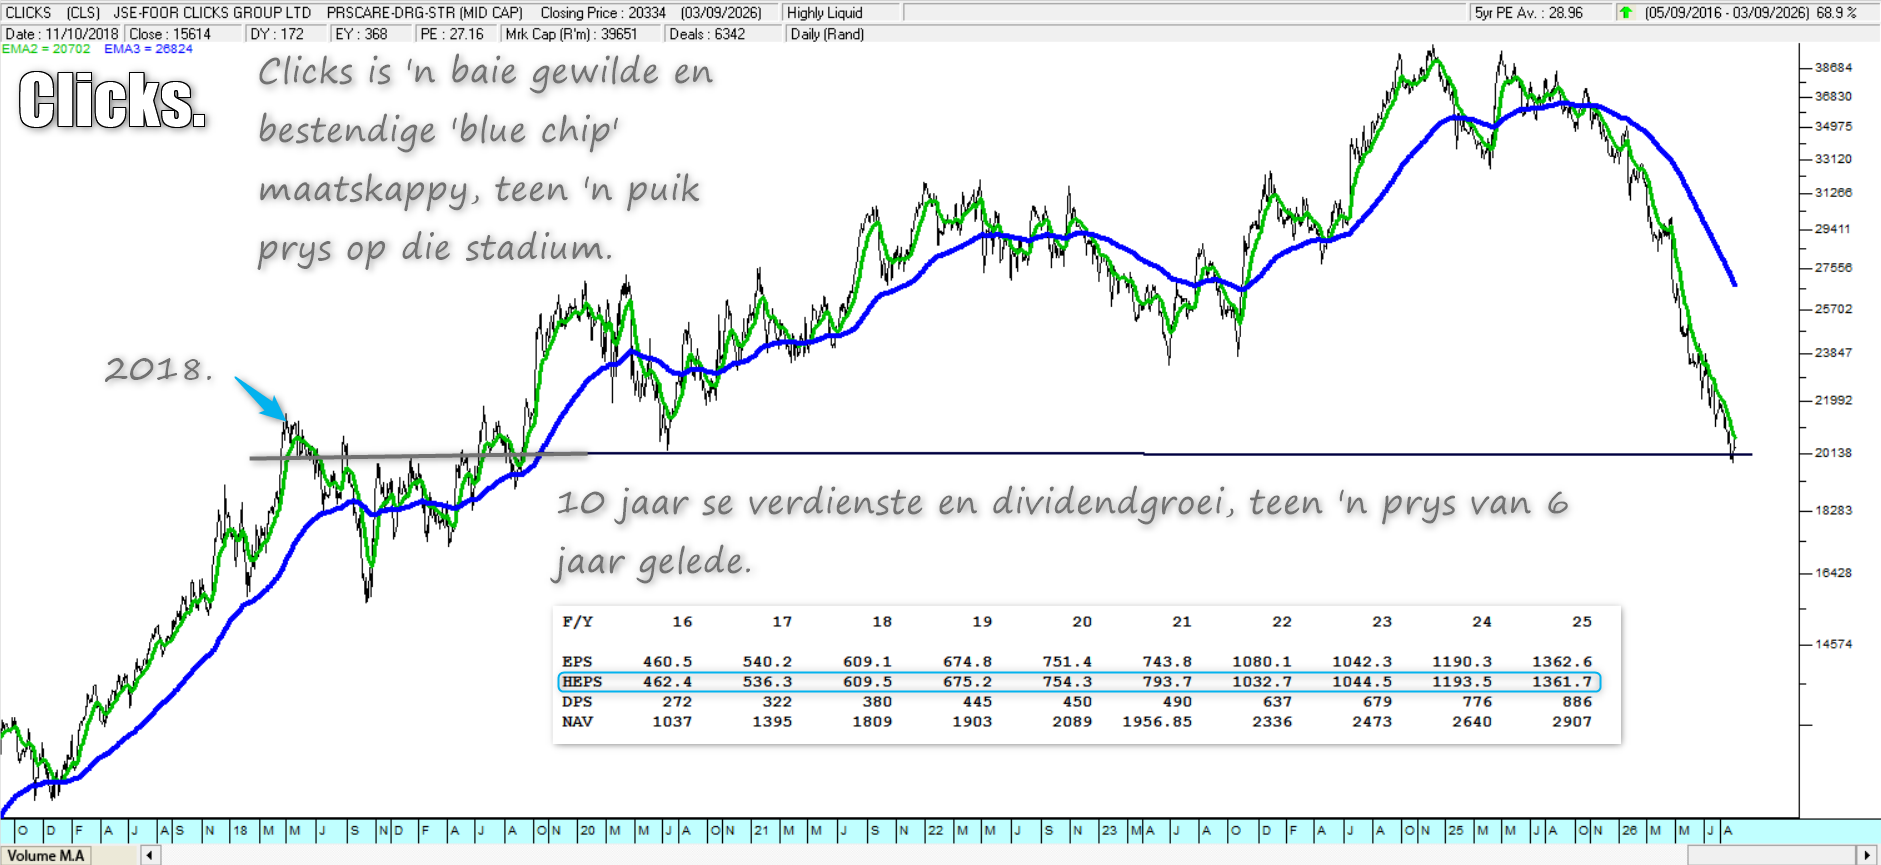
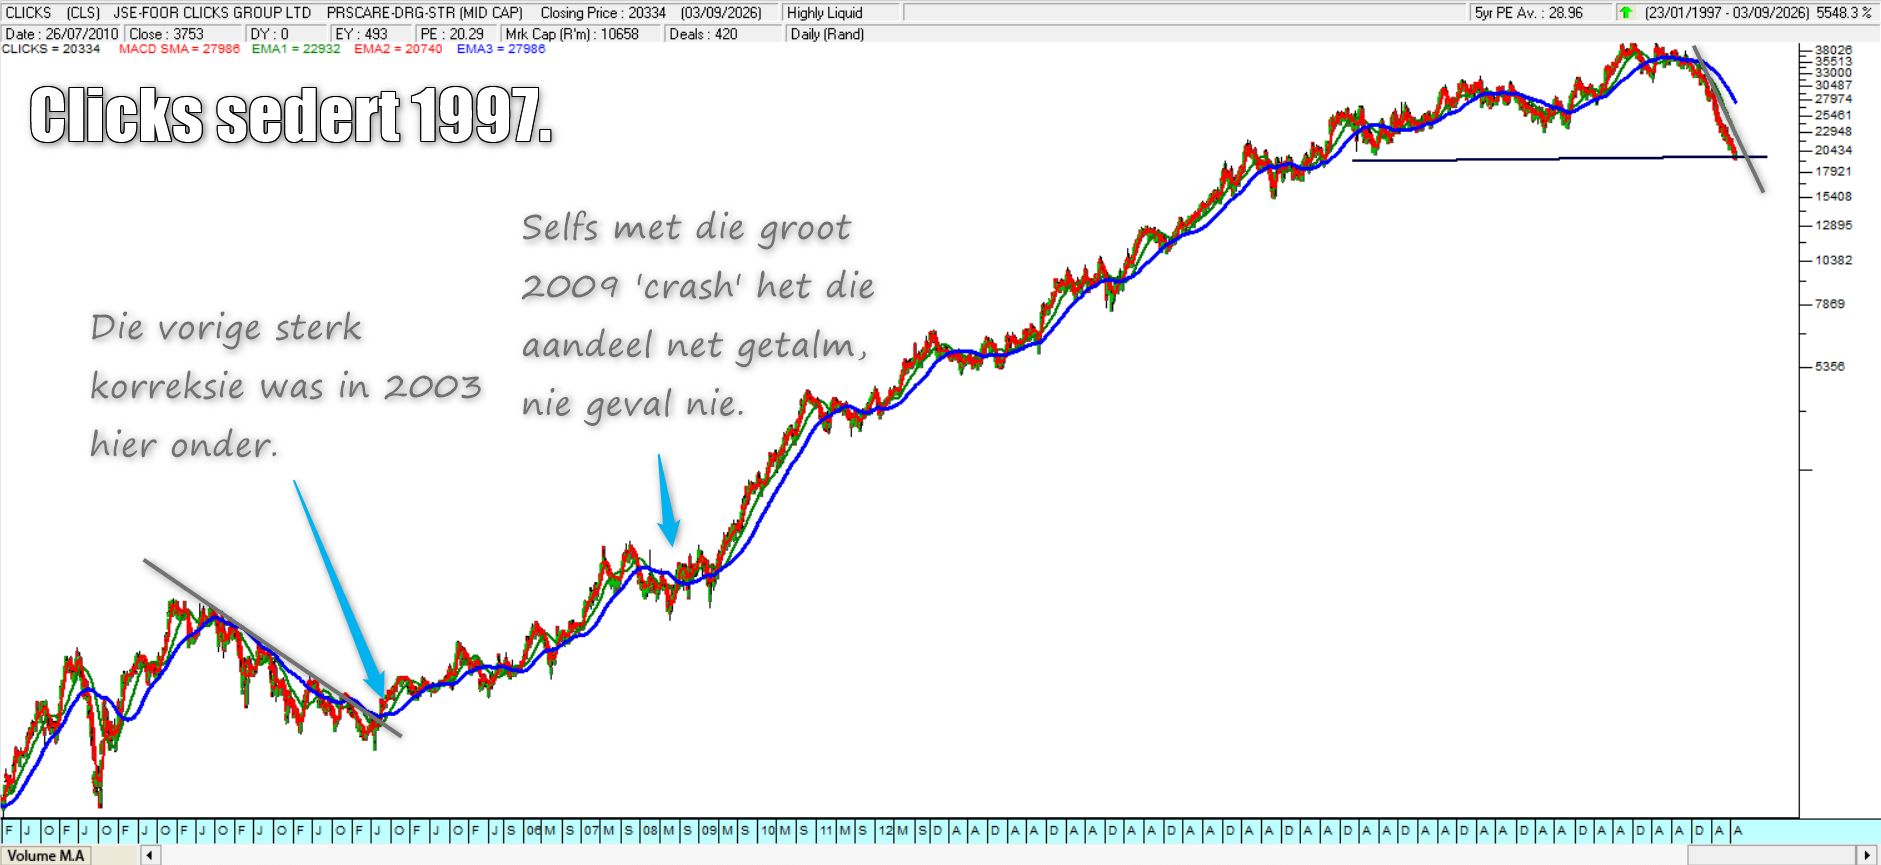
Clicks’ full-year results come out on 23 October [1]. Its half-year results were spot on. So why the strong correction of, look closely, about 50% [2]?
Perhaps it was overpriced. But now, in my view, it is surely underpriced. It needs about 25% [3] just to be priced reasonably normally again. Perhaps it was overpriced six years ago too, after the wild run in its price. But from reading the chart I think it is worth at least 25% more than it is now. If it gets back to its 200-day moving average, that looks like a stronger case to me.
What Simply Wall St says
Simply Wall St also rates Clicks highly, by its own criteria. It reckons Clicks is 17% below its fair value [4]. I reckon closer to 25%, going by the chart, which always overshoots and undershoots around the 200-day moving average.
I also looked at a Simply Wall St “narrative” on Clicks, published in July 2026. It is built on the bullish end of the analysts’ opinions. It puts a fair value of R392 on the share and calls it about 49% undervalued at R200 [5]. In my own words: for that number to work you have to believe in growth of the order the bullish analysts assume, and a much richer price-to-earnings ratio (30.9 times, against 15.7 times today) [6]. The same page notes that the analysts do not agree. Their targets run from R235 at the bearish end to R392 at the bullish end, with a consensus of R327.88 [7]. I read that as a reminder that a “fair value” is somebody’s opinion, not a fact. The narrative also lists risks, among them stretched consumers, tougher competition, and pharmacy expansion and distribution margins [8].
What the chat says
I asked ChatGPT why Clicks is down about 50% and whether there is a solid reason. I think its answer is fairly spot on, but remember it is unverified [9].
As I read the chat, a fall from about R400 to R200 is too big to put down to bad sentiment alone. It saw no fundamental collapse that would justify halving the value. In its words the market mostly destroyed the valuation, not the earnings. It said the share closed at about R199.17 on 4 September, against R362 at the end of August 2025, and that the market value of the company shrank from about R89 billion to about R47 billion [10].
For the business itself, the chat gave these half-year numbers: turnover up 7.4%, pharmacy sales up 8.6%, headline earnings per share (HEPS) up 8.1%, dividend up 8.4%, cash from operations of R1.9 billion and a return on equity of 45.7%. Pharmacy market share rose from 24.2% to 24.9% [11]. That does not look like a company whose economic value has halved.
But there are problems, it said. The biggest is that growth has slowed, while Clicks was priced for very high growth. Management now expects only 4% to 9% growth in full-year HEPS [12]. On top of that, consumers are under pressure, competitors have started discounting aggressively, Dis-Chem is expanding, and supermarkets and online players are pushing into the same categories. A new warehouse management system caused problems and cost about R175 million in sales, and the wholesaler UPD lost two bulk distribution contracts [13]. The warehouse problem looks temporary: according to Clicks, product availability was back at target by the end of February [13].
The chat’s main explanation was the old price-to-earnings ratio. Clicks was simply terribly expensive, and the market paid 30 times earnings or more for years [14]. When growth slows, the market asks why it should pay so much, and the price can fall a long way without earnings falling at all. That is called PE compression. The chat also noted that JPMorgan Chase had reduced its stake to 3.0% [15]. That does not prove anything is wrong, it said, but it shows large institutional money moving out, and that can keep a share under pressure for a long time. It added that the Financial Mail wrote in April that the business was not fundamentally broken [16].
Its summary: at R350 to R400 the share would not have looked attractive, but at R200 it becomes a different story. A business that is still profitable, with growing earnings and dividends, a strong balance sheet and a growing market share. Its preliminary conclusion was that the fall looks like a massive valuation reset, not a Clicks disaster. That could make it an interesting opportunity, provided the next results confirm that growth holds and that competition does not start destroying margins.
Where I stand
With a PE of 14.4 and a dividend yield of almost 4% [17], Clicks is not a rotten proposition, even with the new competition from Dis-Chem included. The way I see it, one approach is to hold until just before the results come out, and then watch how the share fares.
On 22 September I noted that Clicks was on its way, with big volume [18].
I am watching. The results on 23 October will tell me more.
Update: Clicks on its way

Sources
- SOURCE NEEDED: Clicks' full-year results are released on 23 October. No source named. ↑
- SOURCE NEEDED: The Clicks share price has corrected by about 50%. No source named by Koot; the chat gives about R400 to about R200. ↑
- SOURCE NEEDED: Koot's own estimate (from the chart) that the share needs about 25% to be priced normally again, and is worth at least 25% more. This is Koot's opinion. ↑
- SOURCE NEEDED: Simply Wall St's view that Clicks is 17% below its fair value. Source named: Simply Wall St (the figure is from Koot's email of 5 September). ↑
- SOURCE NEEDED: A Simply Wall St community "narrative" (published 16 July 2026, titled along the lines of "Store expansion and healthcare demand will support a stronger long-term outlook") with a fair value of R392 and the share about 48.9% undervalued at R200.28 on 6 September. It is based on the bullish end of analysts' forecasts. Source named: Simply Wall St. ↑
- SOURCE NEEDED: For the bullish case to hold, the company would need to trade at a PE of 30.9 times on 2029 earnings, against 15.7 times today. Source named: Simply Wall St narrative. ↑
- SOURCE NEEDED: Analyst targets from R235 (most bearish) to R392 (most bullish), consensus R327.88. Source named: Simply Wall St narrative. ↑
- SOURCE NEEDED: Risks listed (consumer pressure, competition, pharmacy licences and system rollouts, low-margin wholesale distribution, heavy investment). Source named: Simply Wall St narrative. ↑
- SOURCE NEEDED: The chat's answer on why Clicks is down about 50%. Source named: ChatGPT ("Chat"). Unverified. ↑
- SOURCE NEEDED: Closing price of about R199.17 on 4 September; R362 at the end of August 2025; market value from about R89 billion to about R47 billion. Source named: ChatGPT. Unverified. ↑
- SOURCE NEEDED: H1 2026 figures: turnover +7.4%, pharmacy sales +8.6%, HEPS +8.1%, dividend +8.4%, cash from operations R1.9 billion, return on equity 45.7%, pharmacy market share 24.2% to 24.9%. Source named: ChatGPT. Unverified. ↑
- SOURCE NEEDED: Management expects full-year (FY2026) HEPS growth of 4% to 9%. Source named: ChatGPT. Unverified. ↑
- SOURCE NEEDED: Warehouse system problems cost about R175 million in sales; UPD lost two bulk distribution contracts; product availability back at target by end February according to Clicks. Source named: ChatGPT. Unverified. ↑
- SOURCE NEEDED: The market paid 30 times earnings or more for Clicks for years. Source named: ChatGPT. Unverified. ↑
- SOURCE NEEDED: JPMorgan Chase reduced its stake in Clicks to 3.0%. Source named: ChatGPT. Unverified. ↑
- SOURCE NEEDED: Financial Mail wrote in April that the problem was not that the business is fundamentally broken. Source named: ChatGPT, citing Financial Mail. Unverified; no article named. ↑
- SOURCE NEEDED: Clicks PE of 14.4 and a dividend yield of almost 4%. Source named: ChatGPT (Koot's email). Unverified. ↑
- SOURCE NEEDED: Clicks "on its way, with big volume" on 22 September. This is from the subject line of Koot's email; the chart or data in the attached image is needed. ↑